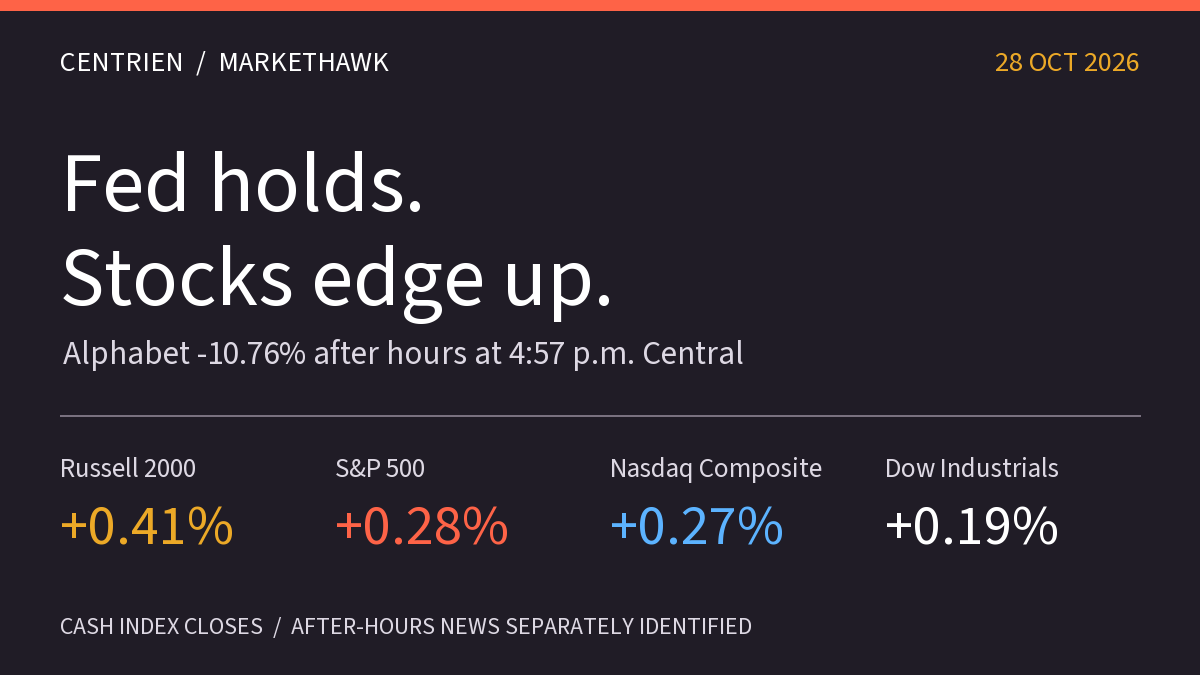
The Federal Reserve held its policy rate in a 10–2 vote, with both dissenters favoring an increase. U.S. stocks finished slightly higher, but the closing scorecard did not capture a sharp earnings reaction after the bell: Alphabet was quoted down 10.76% in after-hours trading at 4:57 p.m. Central.
Four gains, all below half a percent
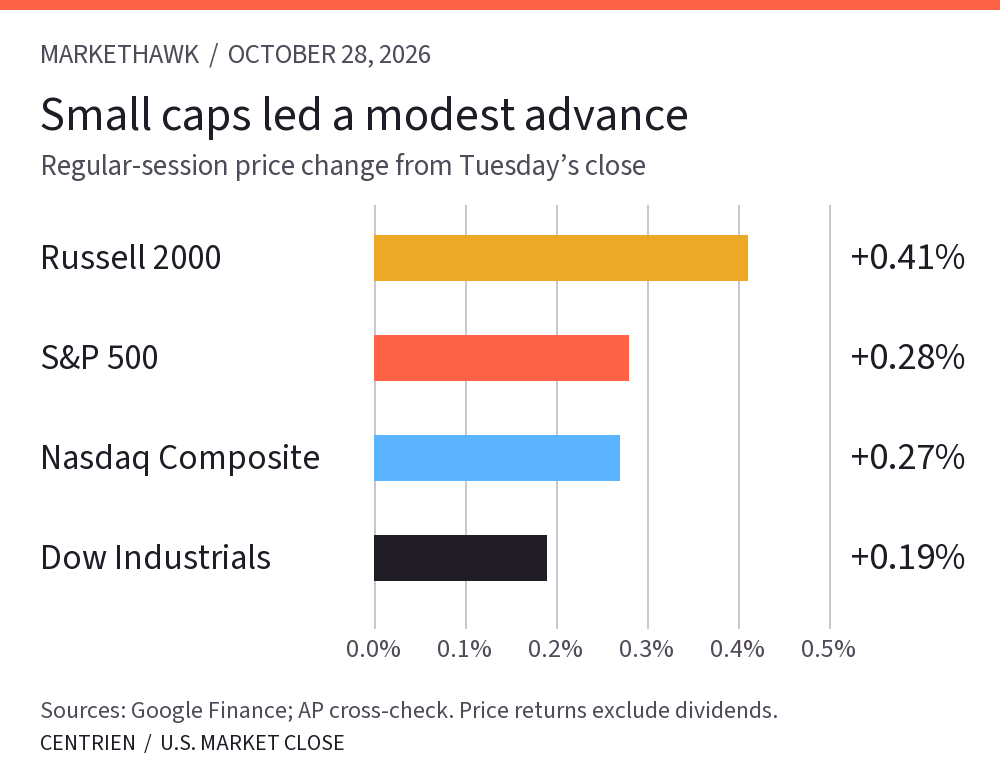
The Russell 2000 led the major benchmarks with a 0.41% advance. The S&P 500 gained 0.28%, the Nasdaq Composite 0.27%, and the Dow 0.19%. These are regular-session cash-index price changes from Tuesday’s close, excluding dividends. The AP closing scorecard agrees with the individual index quotations linked below.
| Index / source | Close | Point change | Price change |
|---|---|---|---|
| Russell 2000 | 2,830.51 | +11.64 | +0.41% |
| S&P 500 | 7,743.98 | +21.38 | +0.28% |
| Nasdaq Composite | 26,549.85 | +72.04 | +0.27% |
| Dow Industrials | 52,475.10 | +97.53 | +0.19% |
Small caps outperforming by a fraction of a percentage point is evidence of relative performance, not a count of advancing companies. The index returns alone do not establish market breadth or show whether an equal-weight portfolio participated to the same degree.
A pause with two votes for a hike
The FOMC’s 1:00 p.m. Central statement left the federal-funds target range at 3.75%–4.00%. Lisa D. Cook and Beth M. Hammack dissented, preferring a quarter-point increase. The committee described economic activity as expanding strongly and inflation as still elevated.
The distinction matters for the next policy decision. An unchanged target range does not remove the possibility of tighter policy later. Two members’ preference for a hike also makes it difficult to interpret the pause as a committee-wide judgment that inflation risks have passed.
The bond market’s reaction was less straightforward than the stock-index gains. AP reported that the two-year Treasury yield initially rose after the decision and subsequently reversed as traders reduced expectations for additional increases.
Technology led; utilities and property funds lagged
Across the eleven Select Sector SPDR funds, six rose and five fell. Technology’s XLK gained 0.80%, ahead of financials’ XLF at 0.45% and energy’s XLE at 0.35%. At the other end, utilities’ XLU lost 0.84%, real estate’s XLRE fell 0.73%, and communication services’ XLC declined 0.42%. These are ETF regular-session price returns used as sector proxies, not the underlying sector indexes or dividend-inclusive returns.
Micron closed at $983.23, up 5.86%, a much larger move than the broad technology fund’s advance. That contrast shows why a strong individual semiconductor stock should not be treated as a uniform move across technology.
The VIX quote was 16.91, down 0.61 point, at 3:15 p.m. Central. In energy, Google Finance’s NYMEX continuous crude-oil series, CLW00, showed $101.94 per barrel, up 2.04%, at 4:00 p.m. Central. That is a timestamped futures-series observation, not a verified settlement price.
Alphabet’s after-hours fall changes the handoff
Alphabet’s issuer release, distributed at 3:06 p.m. Central, reported third-quarter revenue of $127.6 billion, up 25%, and earnings per share of $2.12. Google Cloud revenue was $30.7 billion, up 103%. The release’s host displayed Alphabet at $289.94, down 10.76% after hours, at 4:57:38 p.m. Central. The regular-session quote on the same page was $324.89, up 1.34%.
Those two returns describe different trading windows. The evening decline was not part of Wednesday’s cash-index close, and it is not a forecast for Thursday’s opening price.
Microsoft’s fiscal first-quarter release, covering the period ended September 30, reported revenue of $92.3 billion, up 19%. Microsoft Cloud revenue reached $63.9 billion, up 30%, and Azure revenue grew 48%. GAAP diluted earnings were $4.92 per share; the company’s adjusted figure was $4.89, excluding the impact of its OpenAI investments. Its conference call began at 4:30 p.m. Central.
Growth and inflation arrive together Thursday morning
The next regular U.S. equity session is Thursday, October 29. The confirmed calendar, in Central time:
- 7:30 a.m.: The advance estimate of third-quarter GDP, listed in BEA’s 2026 GDP release schedule, alongside September Personal Income and Outlays, including PCE inflation. The October economic calendar confirms the release time.
- 7:30 a.m.: Weekly unemployment-insurance claims, listed in the Thursday economic calendar.
- 4:00 p.m.: Amazon’s third-quarter results conference call, following the regular equity close.
GDP measures inflation-adjusted activity across a quarter; the monthly PCE price measures address a different part of the policy question. Reading growth alone could miss an inflation surprise in the simultaneous release. The first regular-session prices in Microsoft and Alphabet will also show how the wider cash market receives results that arrived after Wednesday’s index close.
Keep reading.
Your Access List Is a Museum. Time to Clean It Out.
An access review needs more than a list of active employees. Supplier accounts, service identities, inherited permissions, and active sessions can preserve access after the original reason has ended.
3 min read →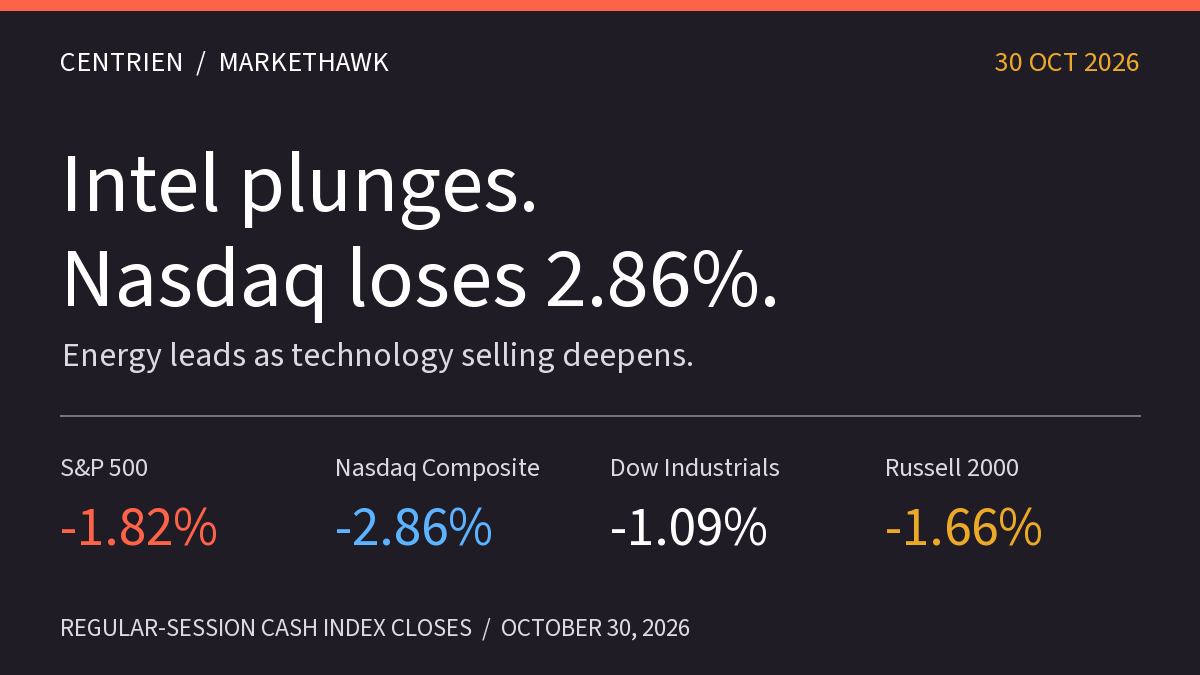
October 30 market close: Intel plunges, Nasdaq falls 2.86%
Intel falls 28.58% as its outlook weighs on technology. Nasdaq loses 2.86%, energy leads sector gains, and labor-cost data and weekly returns frame the Friday close.
4 min read →
October 29 market close: Alphabet sinks, small caps advance
Alphabet falls 12.64% and the Nasdaq loses 1.38%, while small caps and nine sector ETFs gain. GDP, inflation and Amazon earnings frame a sharply divided session.
4 min read →