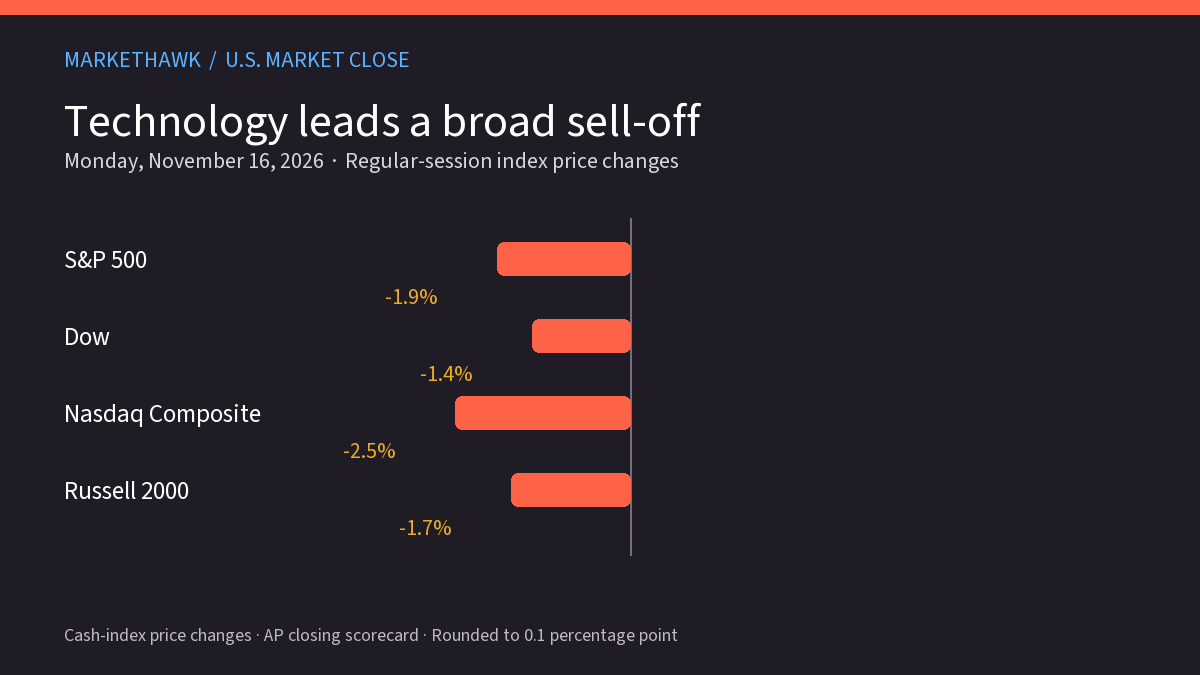
Technology shares drove Monday’s decline, with Nvidia and other chipmakers under pressure. The Nasdaq Composite fell 2.5%, the steepest loss among the four major indexes in the closing scorecard. The S&P 500 logged a third consecutive decline. Treasury yields eased and oil fell, but neither move was enough to offset the equity selling.
All four major indexes finished lower
The S&P 500 lost 145.08 points to close at 7,416.59, down 1.9%. The Dow Jones Industrial Average fell 739.38 points to 51,608.17, a 1.4% decline. The Nasdaq Composite shed 626.52 points to 24,509.76, down 2.5%; the Russell 2000 lost 47.55 points to 2,742.94, down 1.7%. These are regular-session cash-index closes and price changes, not total returns. AP’s closing scorecard reports all four; the S&P close also appears in YCharts’ dated history, while Chase’s market overview lists the Dow and Nasdaq levels and Tallac Options’ Russell index page lists the small-cap close.

| Index | Close | Point change | Change |
|---|---|---|---|
| S&P 500 | 7,416.59 | -145.08 | -1.9% |
| Dow Jones Industrial Average | 51,608.17 | -739.38 | -1.4% |
| Nasdaq Composite | 24,509.76 | -626.52 | -2.5% |
| Russell 2000 | 2,742.94 | -47.55 | -1.7% |
Chipmakers kept pressure on technology stocks
The decline extended last week’s weakness in AI-linked shares. AP reported that Nvidia fell again after the prior week’s resignation of CEO Jensen Huang and that rival chip companies also declined. That concentration showed up in the index results: the technology-heavy Nasdaq fell more than the Dow and small-cap Russell. This comparison describes the day’s pattern; it does not establish that one headline alone caused the move.
Other company-specific moves cut across sectors. L3Harris Technologies fell 3.9% after administration officials suggested the FAA contractor could be at fault in Friday’s nationwide ground stop; the company said it was assisting the investigation. Summit Therapeutics dropped 16.5% after reporting that the FDA indicated it could not approve the company’s lung-cancer therapy application. Tyson Foods rose 8.7% after reporting stronger quarterly profit than expected, while revenue was weaker as beef sales fell year over year. The AP market wrap provides the reported company context.
Technology was the clear lagging sector in the coverage available at the close. The verified closing scorecard did not provide comparable performance for all 11 S&P 500 sectors, so this recap does not assign a numerical sector leader or a full sector ranking.
Yields eased as Brent crude fell
AP reported the 10-year Treasury yield at 5.13%, down from 5.15% late Friday. Brent crude fell 3.5% to $92.44 a barrel in the market wrap. The lower oil price removed one source of inflation pressure during the session, while the yield remained well above its 4.80% low earlier in the month, according to AP. Those readings give context to Monday’s trading; they do not by themselves explain the equity declines.
The New York Fed’s November Empire State Manufacturing Survey, released Monday, showed its general business conditions index at 7.8, down from 25.5 in October. The measure remained above zero, indicating that more surveyed manufacturers reported improving than worsening conditions, but the 17.7-point drop marked a substantial cooling in the month-to-month reading. The survey’s table reports the index and response shares.
Tuesday brings retail sales and Nvidia results
The next regular U.S. equity session is Tuesday, November 17. The Census Bureau schedules its October advance monthly retail trade report for 8:30 a.m. Eastern (7:30 a.m. Central). Nvidia’s investor-relations notice says the company expects to post third-quarter results at approximately 1:20 p.m. Pacific (3:20 p.m. Central), followed by a 2:00 p.m. Pacific earnings call (4:00 p.m. Central). Both events fall after the opening and before the close, making them potential sources of new information during Tuesday’s session. The Census release calendar and Nvidia notice confirm those scheduled times.
Regular NYSE and Nasdaq sessions resume Tuesday under their published 2026 calendars; November 16 was not a full-market holiday.
Keep reading.
Winterizing Commercial HVAC Before the First Hard Freeze
Preparing commercial heating equipment for winter requires attention to safe operation, controls, support, and the site's operating needs. The work should follow the equipment manufacturer's requirements and qualified technical judgement.
3 min read →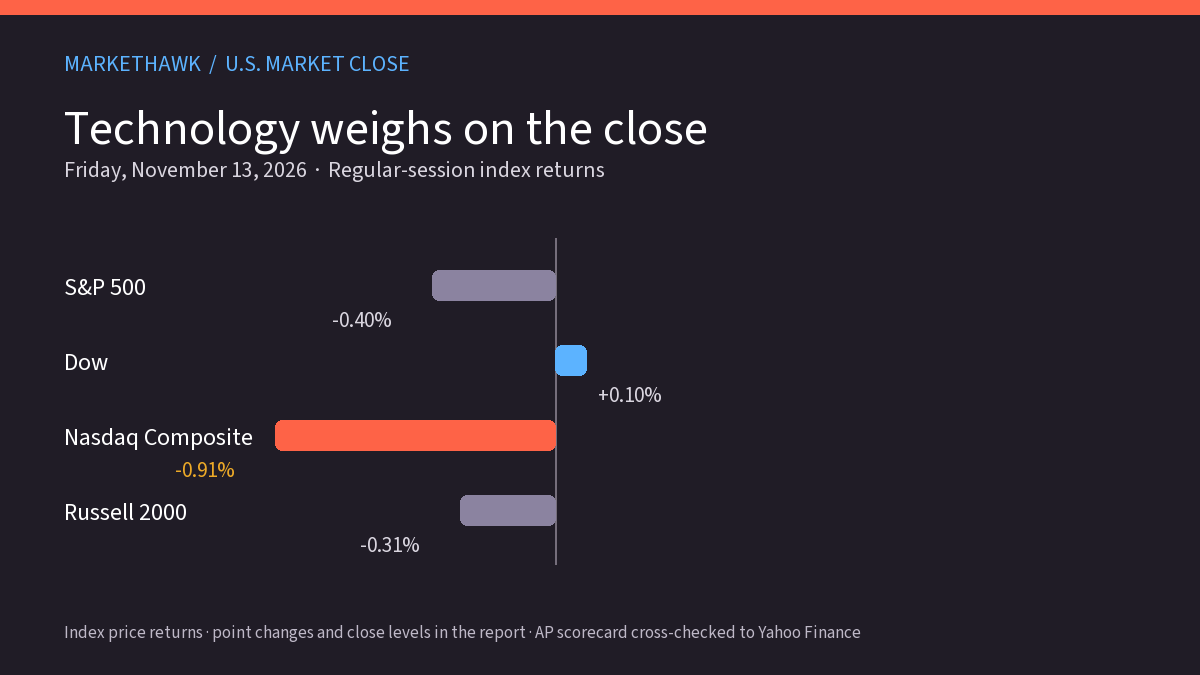
Tech Stocks Weigh on S&P and Nasdaq; Dow Edges Higher
Friday’s close split the major indexes: the Dow rose slightly while technology weakness pulled the S&P 500 and Nasdaq lower. Producer prices cooled monthly but remained elevated year over year.
3 min read →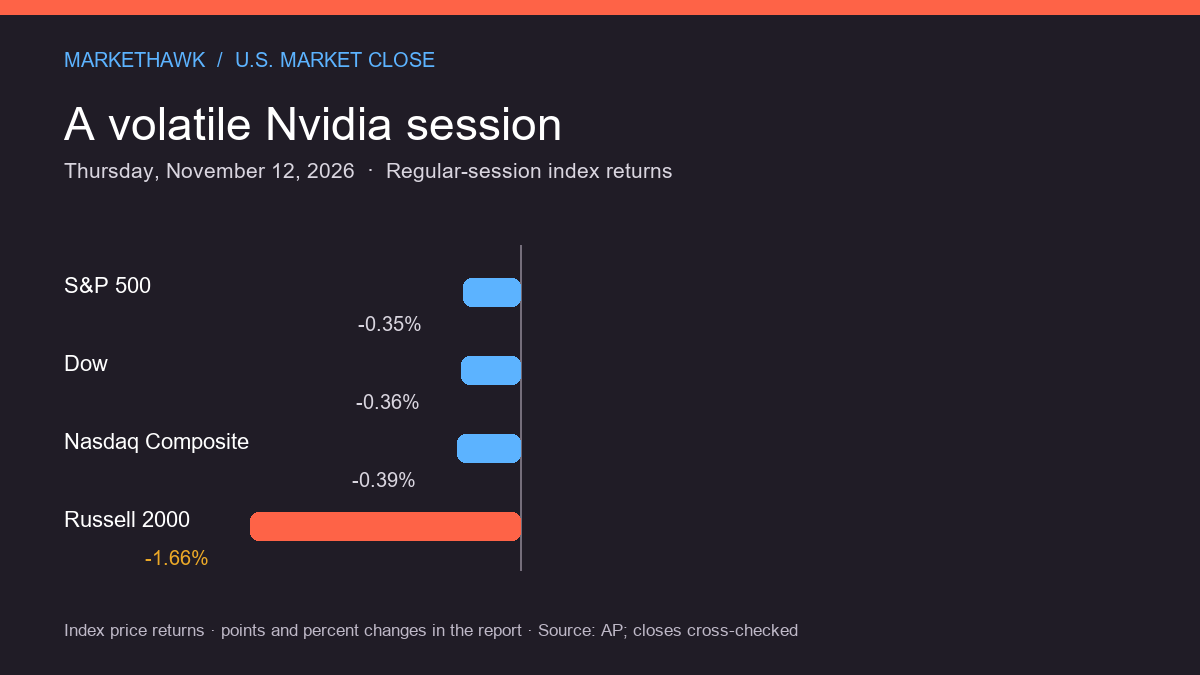
Nvidia’s CEO Exit Jolts Stocks; Oil Rises as Indexes Recover From Early Losses
Nvidia shares plunged after the CEO transition announcement, then pared losses. Energy outperformed, oil rose, and all four major U.S. indexes finished lower.
3 min read →